
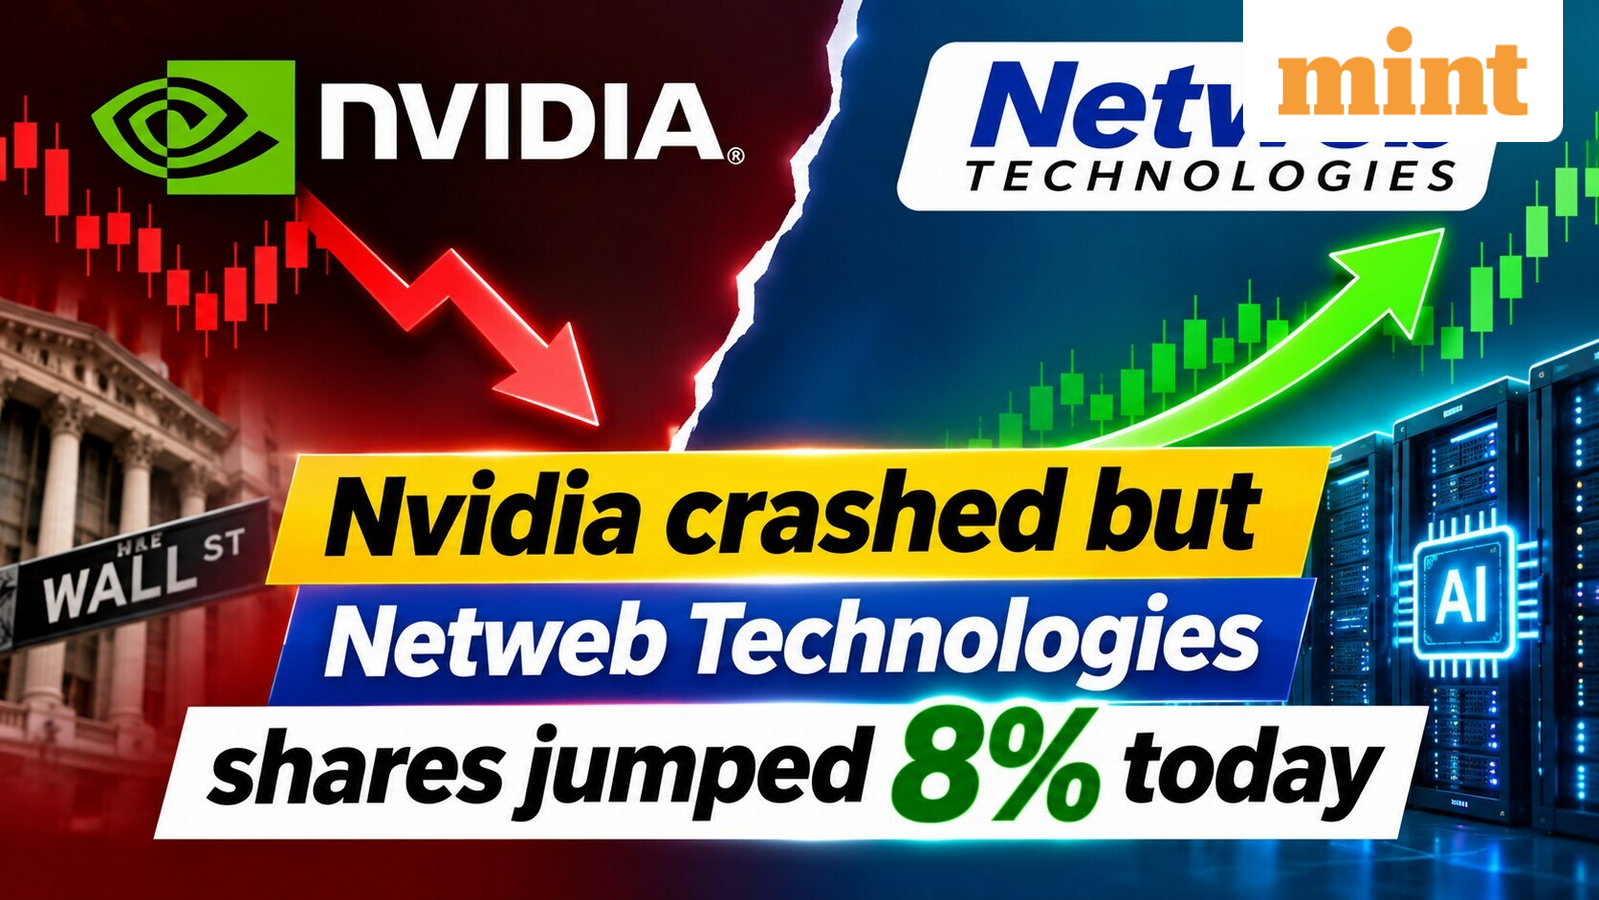
Netweb share price: While global AI heavyweight Nvidia came under pressure on Wall Street, Indian AI infrastructure company Netweb Technologies moved in the opposite direction, with its shares rallying nearly 8% in morning trade on Wednesday, November 11.
While Nvidia shares tumbled 5.5% in overnight trading on Wall Street amid an investigation into CEO Jensen Huang’s relationship with a woman suspected of being a Chinese spy, Indian AI stock Netweb Technologies moved in the opposite direction, surging nearly 8% on Wednesday, November 11.
The contrast is notable given Netweb Technologies’ 15-year partnership with Nvidia, one of the world’s leading AI chipmakers. Huang has acknowledged the reported relationship and apologised, while US President Donald Trump said the FBI was investigating the matter. Nvidia’s independent board members have also brought in law firm Wachtell, Lipton, Rosen & Katz to assist with the probe.
Despite the pressure on its global technology partner, Netweb Technologies shares attracted strong buying interest, supported by value buying following a recent correction and the company’s record September-quarter earnings.
In today’s deals, the stock advanced as much as 7.8% to an intra-day high of ₹4141.75 per share. However, it remains around 28% below its 52-week high of ₹5,810, recorded in August 2026. Its 52-week low stands at ₹2,942.45, touched in December last year.
The stock had declined 13% in one month and 15% over three months before Wednesday’s rally. The company’s strong Q2 FY27 performance, growing AI infrastructure business and sizeable order pipeline have provided fresh triggers for investor interest.
Why is Netweb Technologies share price rising today?
The rebound in Netweb Technologies shares was supported by improving sentiment across technology stocks. The Nifty IT index jumped around 4%, as heavyweight IT and technology companies witnessed strong buying interest. The recovery in the sector also supported high-growth companies operating in the AI infrastructure space, including Netweb Technologies, which had recently faced selling pressure.
Its September-quarter earnings provided a stronger fundamental trigger. Netweb reported consolidated profit after tax (PAT) of ₹136.7 crore in Q2 FY27, compared with ₹31.4 crore in the corresponding quarter last year. Revenue from operations more than quadrupled to ₹1,323.3 crore from ₹303.7 crore.
The company also maintained strong sequential momentum. Revenue increased 61.5% from ₹819 crore in Q1 FY27, while net profit climbed 60.6% from ₹85.3 crore. EBITDA rose 64.4% to ₹197 crore from ₹119.8 crore, accompanied by an improvement in EBITDA margin to 14.9% from 14.6%.
Another important indicator was the company’s order book, which stood at ₹2,629 crore as of September 30, 2026. This provides visibility into execution opportunities over the coming quarters.
Chairman and Managing Director Sanjay Lodha said the company had delivered another record quarter, achieving its highest-ever quarterly revenue and PAT. He also highlighted that first-half FY27 PAT had reached ₹222 crore, exceeding the full-year FY26 profit of ₹205.8 crore.
Should you buy Netweb Technologies shares?
Brokerage outlooks have remained positive, with analysts pointing to India’s expanding AI infrastructure requirements, Netweb’s technological capabilities and its growing order pipeline.
BofA Securities initiated coverage on the company with a ‘Buy’ rating and a target price of ₹5,000 per share, implying an upside potential of 34.5% from current levels. The brokerage sees Netweb as a key beneficiary of India’s expanding AI infrastructure buildout.
Its competitive positioning is supported by a 15-year partnership with NVIDIA, established expertise in supercomputing and long-standing relationships with key government customers. BofA expects revenue to grow at a compound annual growth rate (CAGR) of 40% between FY26 and FY29. It also anticipates operating leverage benefits as the business scales, allowing the company to remain competitive on pricing despite a high-inflation environment while maintaining broadly stable profitability.
Equirus maintained its ‘LONG’ rating and revised its December 2027 target price to ₹5,560 from its earlier September 2027 target of ₹5,390. The revised valuation is based on a forward price-to-earnings (PE) multiple of 51 times estimated EPS of ₹109, compared with the earlier valuation of 56 times EPS of ₹96.2.
It highlighted the improving growth visibility, backed by a sizeable pipeline of prospective orders and projects where the company has emerged as the lowest bidder.
Netweb needs to tighten its working capital and FCF generation on a consistent basis,” the brokerage said.
Disclaimer: The views and recommendations made above are those of individual analysts or broking companies, and not of Mint. We advise investors to check with certified experts before making any investment decisions.

Leave a Reply