
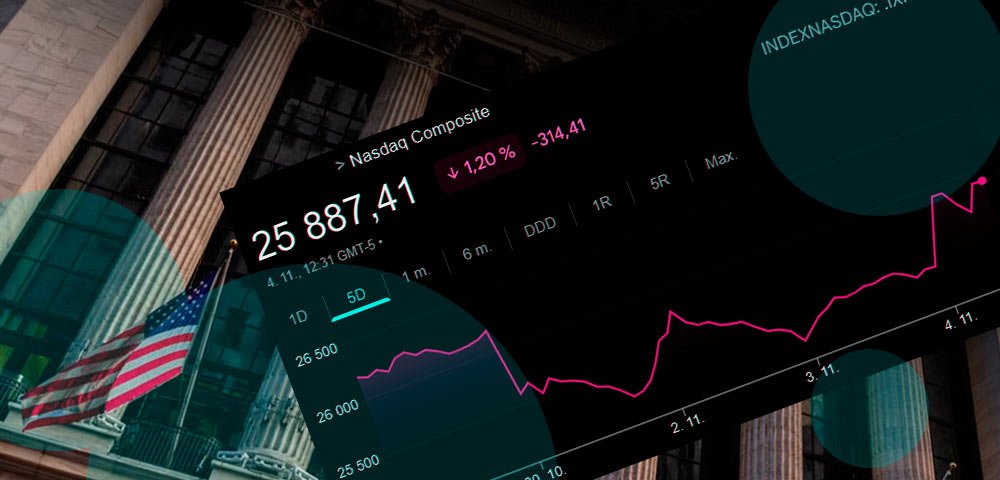
The Nasdaq Composite rallied on Wednesday, November 4, 2026, after Democrats won control of both chambers of Congress, triggering a recovery in major technology stocks following October’s sharp correction.
The index climbed 540.38 points, or 2.13%, to 25,912.39. Amazon gained approximately 7%, Alphabet advanced more than 3%, and Meta Platforms also traded higher. However, the rebound was uneven.
- The Nasdaq Composite gained 2.13% to 25,912.39 on November 4 as Amazon, Alphabet and other major technology stocks recovered.
- Citi, Morgan Stanley and Bank of America warn that new restrictions on data center construction could delay AI investment and pressure semiconductor earnings.
- Investors are distinguishing profitable technology companies from infrastructure businesses dependent on continued capital spending and external financing.
Companies involved in AI infrastructure development continued to face selling pressure as investors assessed the possibility of new restrictions on data center construction.
The divergence followed a difficult October for technology stocks, during which concerns about rising capital expenditure, weaker free cash flow and expensive semiconductor valuations triggered substantial losses.
The Nasdaq-100 entered correction territory earlier this week after falling more than 10% from its October 6 record.
Although the Nasdaq Composite and Nasdaq-100 are different indexes, the latter’s decline illustrates the extent of selling among major technology companies.
Citi warns AI stocks face new regulatory risks
Citi Research expects the Democratic election victory to create additional uncertainty for companies involved in AI infrastructure.
Scott Chornert, the bank’s head of US equity strategy, considers the election an important reduction in political uncertainty for the broader market. However, Citi sees significant risks for semiconductor suppliers and data center operators.
Democratic victories in Texas, Georgia and other major technology investment markets have increased the likelihood of restrictions on new computing facilities.
Texas Governor-elect Gina Hinojosa has proposed a moratorium on new data center construction, citing electricity costs, water consumption and pressure on local communities.
Texas represents a substantial share of planned US computing capacity.
Any significant delay in new projects could affect demand for advanced processors, networking equipment, memory chips and electrical infrastructure.
Citi’s concern is that slower project development could change semiconductor earnings expectations even if demand for AI services remains strong. This distinction helps explain Wednesday’s market performance.
Large cloud providers recovered, while several companies directly involved in expanding data center capacity continued to decline.
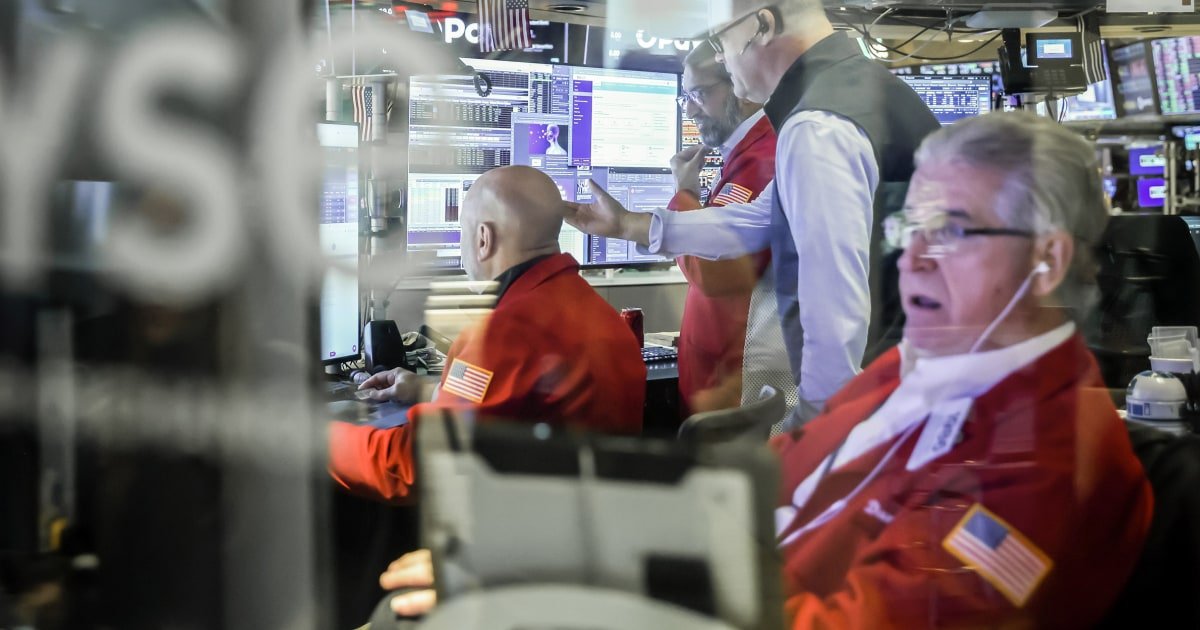
Stock Market Today: US stocks surge after Democrats sweep Congress. Dow, S&P 500 and Nasdaq rally as Goldman Sachs, Morgan Stanley and Citi assess the market outlook.
Morgan Stanley expects AI investment to continue under tighter conditions
Morgan Stanley Research does not expect the Democratic victory to end the US AI infrastructure expansion. Instead, the bank anticipates a more conditional investment cycle.
Ariana Salvatore, a Morgan Stanley strategist covering US public policy, has highlighted the growing importance of state and local authorities in determining where and how data centers are built.
Electricity connections, water permits, zoning restrictions and utility pricing are largely controlled outside Washington.
Consequently, changes in state governments may have a greater immediate effect on AI infrastructure than congressional legislation. Dow Jones forecast: Dow surges 1,200 points as Wall Street bets on political gridlock.
Morgan Stanley expects projects to face increasing requirements relating to energy supply, local infrastructure and construction approvals.
The bank also anticipates a shift in investor attention from computing capacity toward the economics of financing and operating data centers.
Its broader AI research indicates that access to capital, electricity generation and infrastructure efficiency are becoming increasingly important competitive advantages. AI-related debt issuance has reached approximately $471 bn in 2026, according to Morgan Stanley’s market analysis.
The S&P 500 rallied as investors reassessed US political risks following the Democratic victory in the midterm congressional elections.
That raises questions about which companies can maintain investment without weakening their balance sheets or returns on capital.
Bank of America expects slower and more expensive AI development
Bank of America believes the election could create additional costs for the AI industry without fundamentally reversing its growth.
Economist Stephen Juneau expects local restrictions to slow the development of new infrastructure and increase project expenses. These costs may include electricity supply agreements, permitting, grid connections and environmental requirements.
For companies such as Nvidia, Broadcom and Micron, the main risk is a slowdown in the pace of orders. For cloud providers, the financial implications could be more favorable in the short term.
Amazon, Alphabet and Microsoft have committed substantial resources to AI infrastructure. Restrictions that delay some spending could reduce near-term capital expenditure and improve free cash flow.
However, slower investment could also limit future computing capacity and revenue opportunities.
The market is therefore assessing two competing effects: lower investment costs for hyperscalers and potentially weaker demand for their hardware suppliers.
RBC Capital Markets highlights pressure on technology valuations
RBC Capital Markets’ head of US equity strategy Lori Calvasina considers the midterm results more significant for equity investors than many had anticipated.
RBC identified weakness in AI and large-cap growth stocks as a major factor behind the initial overnight decline in futures.
The market subsequently reversed direction, but the early reaction demonstrated how sensitive technology valuations have become to regulatory developments.
High-growth companies are particularly exposed to changes in discount rates and long-term earnings assumptions.
If new restrictions delay data center construction, investors may need to revise assumptions about future semiconductor sales and cloud infrastructure capacity.
That creates the possibility of lower valuations even if underlying demand for AI technology continues expanding.
AMD was among the exceptions to Wednesday’s semiconductor weakness.
The company reported third-quarter revenue of $13.3 bn and issued stronger-than-expected guidance, supported by demand for data center processors.
AMD shares gained approximately 5% during early trading. The results demonstrate that individual semiconductor companies can continue delivering strong growth despite broader concerns about AI spending.
Nvidia, Broadcom and Micron faced a less favorable market reaction.
Investors are increasingly questioning how long semiconductor companies can sustain rapid earnings growth if customers reduce or delay infrastructure investment.
The distinction between demand and profitability is becoming more important.
AI computing requirements may continue rising, but semiconductor earnings also depend on pricing, margins, product competition and the timing of customer orders.
Companies with strong order visibility and diversified customers may prove more resilient than businesses dependent on a limited number of large AI projects.
Oracle and cloud financing remain important risks
The financing of AI infrastructure has become a central concern for technology investors. Oracle announced plans on November 2 to raise $20 bn through a combination of common stock and senior debt.
The company intends to use the proceeds for corporate purposes, including capital expenditure and debt repayment. Its financing plans contributed to renewed scrutiny of borrowing costs and balance-sheet leverage.
Amazon has also faced questions about the sustainability of its capital expenditure program after reporting negative trailing free cash flow of approximately $42 bn.
Although AI investment can support substantial future revenue, the financing costs are immediate.
Morgan Stanley’s research indicates that investors are becoming less willing to overlook these cash flow pressures.
For the Nasdaq, this creates a more selective market in which earnings quality and balance-sheet strength could become more important than projected AI revenue growth alone.
Nasdaq forecast for November and year-end 2026
The investment bank outlook suggests that the technology sector remains supported by long-term AI demand, but the conditions for sustained stock market gains have become more demanding.
Morgan Stanley expects the infrastructure investment cycle to continue, subject to tighter financing and regulatory requirements.
Citi sees the potential for weaker semiconductor earnings expectations if data center construction slows.
Bank of America anticipates higher development costs, while RBC emphasizes the sensitivity of large-cap technology valuations to shifts in investor sentiment.
Three conditional scenarios are relevant:
- Bullish forecast: 26,500-27,500. Strong technology earnings, improved cash flow and stable interest rates support a broader sector recovery.
- Base forecast: 25,000-26,500. The Nasdaq consolidates as gains in major cloud providers are partly offset by weakness in semiconductors and infrastructure companies.
- Bearish forecast: 23,500-24,500. Further AI spending reductions, project delays or rising Treasury yields trigger renewed valuation pressure.
These are independent analytical scenarios, not official Nasdaq targets from the investment banks.
The next important developments include the October US employment report on November 6, future Federal Reserve policy decisions and additional guidance on AI infrastructure expenditure.
Investors will also monitor whether newly elected state governments introduce restrictions affecting major data center projects.
For the Nasdaq, Wednesday’s rally does not resolve the concerns that drove October’s correction.
The longer-term outlook depends on AI demand translating into sustainable earnings and free cash flow, particularly among companies undertaking the largest infrastructure investments.
Technology stocks can recover without every part of the AI industry participating. The durability of that recovery will depend on whether earnings growth can justify current valuations.

Leave a Reply