
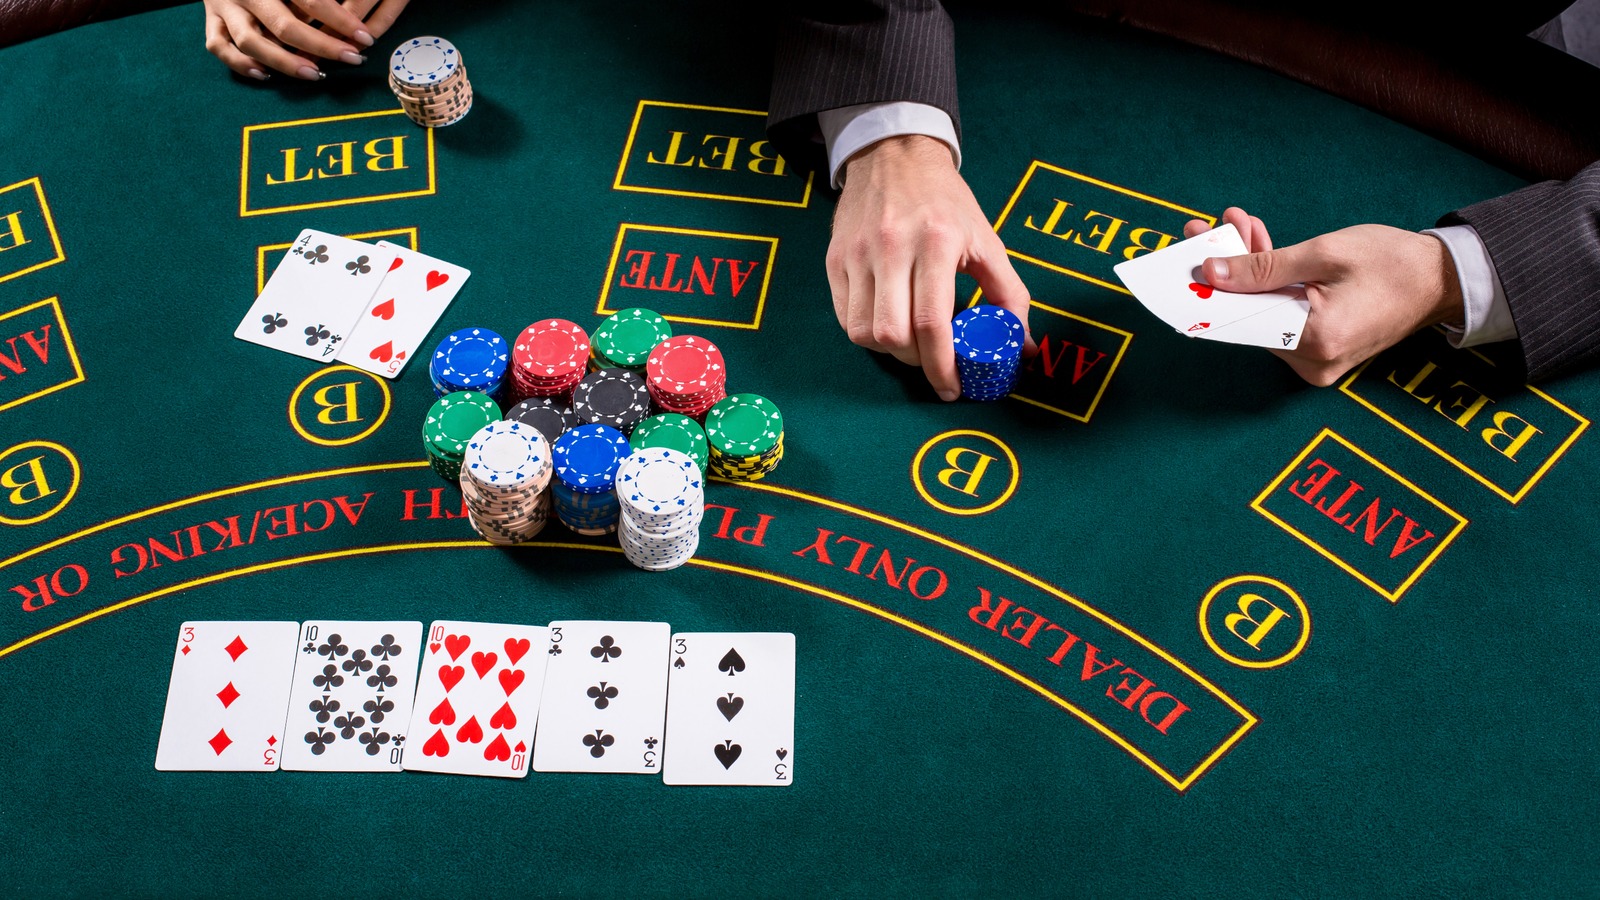
Monarch Casino & Resort (MCRI) just picked up a high profile tourism win, with its Monarch Casino Resort Spa near Denver named America’s No. 1 hotel spa in USA Today’s 2026 Readers’ Choice Awards.
The spa accolade lands while Monarch Casino & Resort’s share price has climbed 23.04% year to date to US$118.17, even after a 30 day share price return that declined 2.76% and a 90 day move that fell 6.81%. Long term total shareholder returns of 19.03% over one year and almost doubling over three and five years point to momentum that has largely been building rather than fading.
Scan for more hospitality and gaming plays with similar momentum by sorting our hand picked 19 high quality undiscovered gems that pair strong fundamentals with under the radar stories.
After a near 100% total return over five years and a fresh US$118.17 share price, Monarch Casino & Resort now faces a sharper question: Does the current valuation still leave enough upside to justify the risk?
Price-to-Earnings of 18.5x: Is it justified?
On traditional metrics, Monarch Casino & Resort screens as good value, with a P/E of 18.5x against a peer average of 51.5x and an industry average of 18.9x, even though the share price has already moved to $118.17.
The P/E ratio compares what investors pay today with the company’s earnings per share, so it effectively shows how much the market is willing to pay for each dollar of profit. For hospitality and gaming, where earnings can swing with tourism cycles and consumer spending, the P/E often captures how confident investors are about those profits holding up.
Here, the current multiple looks compressed versus similar companies and only roughly in line with the broader US Hospitality group. This suggests the market is not pricing Monarch Casino & Resort anywhere near the richer peer levels. Against an estimated fair P/E of 14.5x, the shares trade at a premium to that fair ratio. This points to the possibility that valuation could settle closer to that level if sentiment or earnings expectations cool.
Relative to its industry, the 18.5x P/E sits almost neck and neck with the 18.9x sector average, yet it is materially lower than the 51.5x peer group figure. This is a strong signal that the wider comparison set is carrying far loftier expectations than this stock.
Explore the SWS fair ratio for Monarch Casino & Resort.
Result: Price-to-Earnings of 18.5x (UNDERVALUED).
Still, the story can unravel quickly if tourism demand softens or if Monarch Casino & Resort faces higher operating costs that pressure current earnings.
Find out about the key risks to this Monarch Casino & Resort narrative.
Another view on Monarch Casino & Resort’s value
The SWS DCF model pulls in a very different signal for Monarch Casino & Resort. With the stock at $118.17 and an estimated future cash flow value of $182.91, it indicates that the shares are undervalued according to this approach. That kind of gap raises a simple question: which lens do you rely on when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.

Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Monarch Casino & Resort for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
Mixed signals on Monarch Casino & Resort so far? If the combination of upside potential and flagged issues has your attention, consider acting promptly and pressure test the story against the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Monarch Casino & Resort?
If Monarch Casino & Resort has sharpened your focus on valuation and momentum, keep going. Use the tools available and give yourself more quality shots on goal.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Leave a Reply