
- Banks are prioritising responsible AI deployment over speed, focusing on regulatory compliance and trust in financial services.
- AI is transforming banking workflows with human oversight helping systems learn and manage exceptions.
- Financial institutions are favouring reliable, verifiable AI over the newest models, prioritising safety and accountability over rapid adoption.
In the last few months, a series of essays, statements, and revelations from major tech leaders dominated headlines, sparking global unrest over the exponential speed at which artificial intelligence (AI) is advancing and fueling a newfound push for regulation.
Having endured multiple economic recessions and financial crises, trade finance and payments professionals are no strangers to regulation. Meanwhile, the theme for this year’s Sibos conference in Miami, Florida, was ‘digital finance for AI-driven economies’ in an ode to how automation is transforming the industry.
But how far can banks push AI while operating within a landscape inherently built around guardrails?
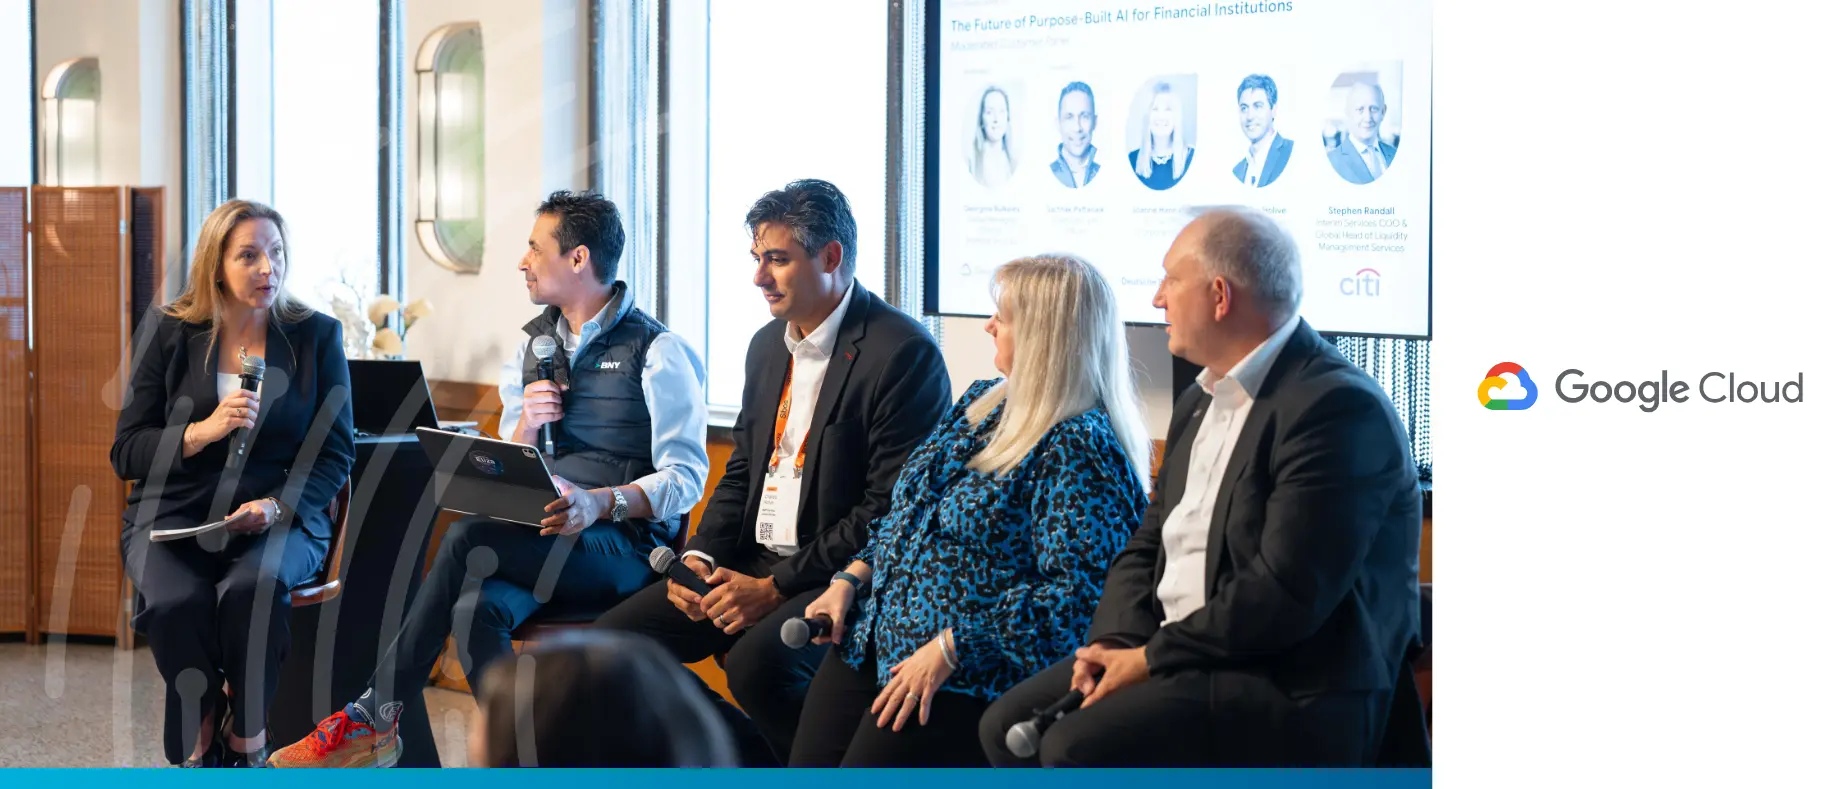
At the Google Cloud Media Breakfast with Alphabet Finance, Deutsche Bank, BNY, BNP Paribas, and Citi, held alongside Sibos in Miami, Florida, experts discussed why being ‘first’ may not always be the priority when it comes to AI.
The banks, in a session moderated by Google Cloud, shared examples of how they have been using AI, and the message was clear: the goal is to train AI and employees to work in harmony, and guardrails aren’t something to fear but to embrace. Rather than being the first to deploy the newest available AI tools, banks must aspire to be the first to deploy them responsibly.
Why generic AI falls short in finance
Caught in the crossfire between rapid innovation and a deep-rooted sense of caution, financial institutions must decide whether they join the race for the newest technology or risk falling behind – while maintaining the trust and regulatory rigour that underpins this industry. Or, perhaps, there is a third option that strikes the right balance.
For over a decade, tech companies and financial firms have been working in tandem, laying the foundations for a digital transition that is now well underway.
This partnership has only strengthened in recent years, in part, due to a ‘capability gap’: general-purpose AI is definitely powerful, but not fully equipped to handle the complexity and data requirements that shape banking workflows.
The industry requires more than a ‘bot’ that can simply answer questions one at a time. Rather, it seeks a model capable of carrying out an ‘end-to-end’, multi-step operation. “More like a digital employee” than a chatbot, said Sarthak Pattanaik, Chief Data and AI Officer at BNY.
In response, tech giants are now offering AI-powered products that are designed specifically for the financial sector. For instance, Google Gemini’s dedicated financial services product adds an industry layer that combines specialised data, domain expertise and, hopefully, strict regulatory controls. The broader promise, according to Pattanaik, is to “structurally amplify how we improve the efficiency of financial markets.”
But as AI autonomy grows, so does the question of human judgement: where does AI fit in a risk-conscious domain?
Different approaches to AI deployment
Well, according to the panellists, it has already found its place.
At BNP Paribas, a trade-break process was redesigned from 10 steps to six, with an agent taking on the first three. Initially, it successfully triaged the majority of cases and repeatedly flagged the exceptions it could not resolve. Rather than handing those incidents back to employees, human intervention was utilised to teach the agent how to handle them. And, within weeks, the workflow became nearly entirely automated. ‘Give a man a fish, feed him for a day; teach him to fish, feed him for a lifetime’.
Meanwhile, at Deutsche Bank, the focus is less on automation and more on what AI can reveal.
Its ‘financial insights’ tool combines market dynamics, financial intelligence, and client data to generate specific, tailored recommendations and carry out subsequent tasks, including credit assessments and analysis, explained Jo Hannaford, Chief Information Officer and Chief Product Officer at Deutsche Bank. On the other hand, at BNY, AI ambition was summarised as “everyone, everywhere, everything.”
In the financial sector, that means moving away from AI as a set of standalone mechanisms towards a more integrated model, in which employees build and use AI themselves. The technology is not only embedded across client, employee, and supplier touchpoints, but is also applied to core processes, from instruction processing to reconciliation and liquidity management.
However, “trust is the one thing we cannot compromise,” said Charles Holive, Corporate and Institutional Banking, Chief AI Officer at BNP Paribas. And the further AI spreads through an institution, the more there is to keep trustworthy.
Every new job handed to AI adds to the oversight a bank needs, and if the controls around the system can’t be trusted, neither can the system.
Slower can mean smarter
This tension came into sharper focus during the audience Q&A, prompted by a question about recent reports regarding OpenAI delaying new models over rising safety concerns. Should banks make the same calculation?
For Holive, the answer lay in demand. “None of us strictly need newer, bigger foundation models right now,” he said.
He also warned that some newer reasoning models offer less visibility into how they reach their answers, which he called an “unacceptable risk” in a regulated industry. His position was that banks should be willing to trade speed for greater control: “I’m happy to be one generation behind on the raw model if it means having superior harnesses, guardrails, and deterministic verification.”
His point, simply put, was that the newest technology is not always the most useful when understanding and verifying its output matters as much as the output itself.
Other panellists offered much of the same logic, arguing that the challenge now lies in turning existing capabilities into safe business results, and adding that institutions may not move at reckless haste, while also ensuring that they are enterprise-ready and safe.
—
The financial sector may be one of the clearest examples of why AI adoption should not be treated as a race. When a bank moves trillions of dollars a day, a hallucinated figure or an unexplained decision isn’t just an embarrassment: it can mean regulatory penalties, significant financial losses, and a permanently damaged reputation.
So, the real measure of progress may not be how quickly banks adopt AI, but what they insist on preserving as they do.

Leave a Reply